


Jul 14, 2026 · 7 min read
Documenting Monsoon Storm Damage: A Checklist for Arizona Owners
The first 72 hours after a microburst decide how strong your claim will be. Here is what to capture before cleanup erases the evidence.
Independent property claim appraisal · all 15 counties
The insurer accepted your monsoon, hail, water or fire claim, but the check won’t cover the repair. As your Arizona Insurance Appraiser, we build an independent line-item valuation and carry it through the appraisal process already written into your policy.
The short-pay problem
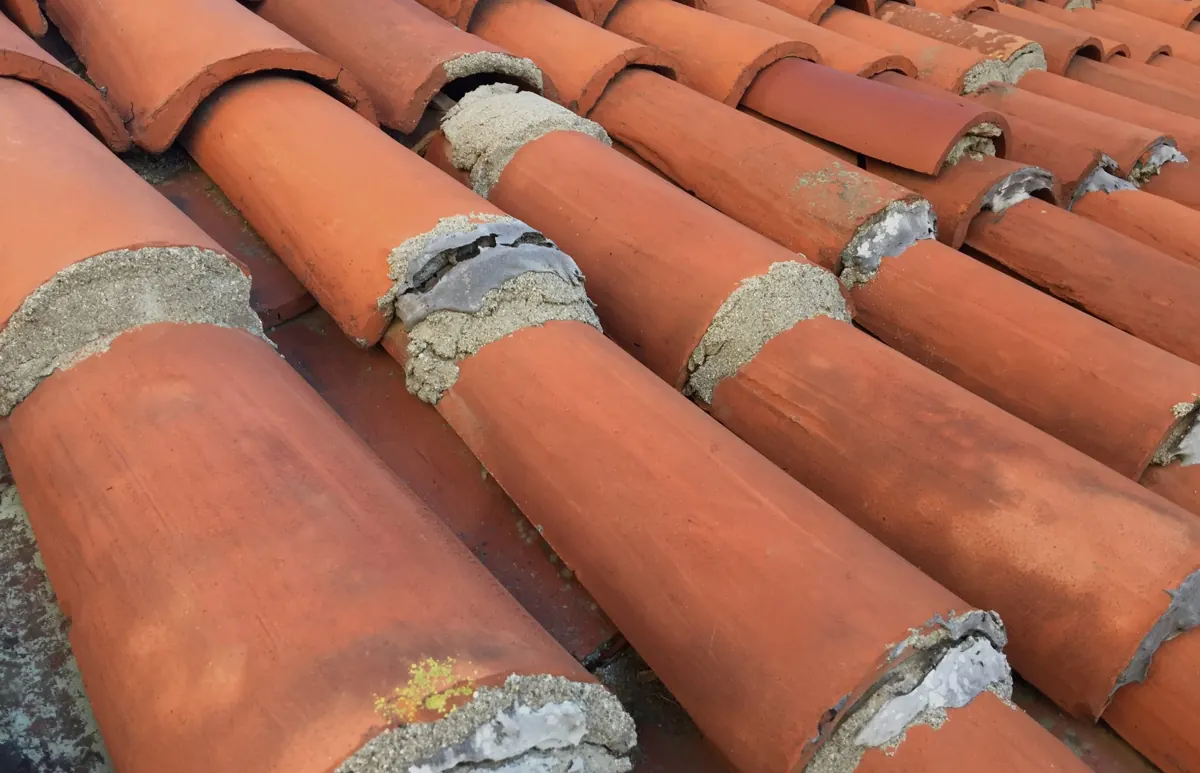
Most disputed Arizona claims are not denials. The carrier pays something, just not enough: a tile roof priced as a few spot repairs, a block wall left off a monsoon claim, a slab leak scoped as one wet room. An Arizona Insurance Appraiser works in exactly that gap between “covered” and “paid.”
We are independent estimators who serve as the appraiser you name under your policy. Arizona Insurance Appraiser never edits the carrier’s estimate; we measure, count and price the loss ourselves, so every line can be defended in front of an umpire.
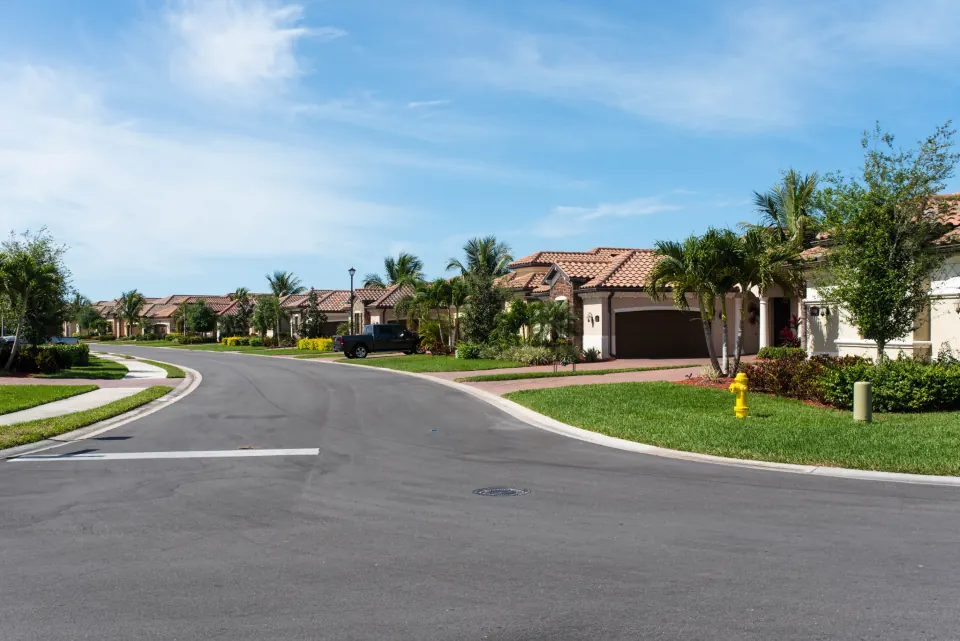
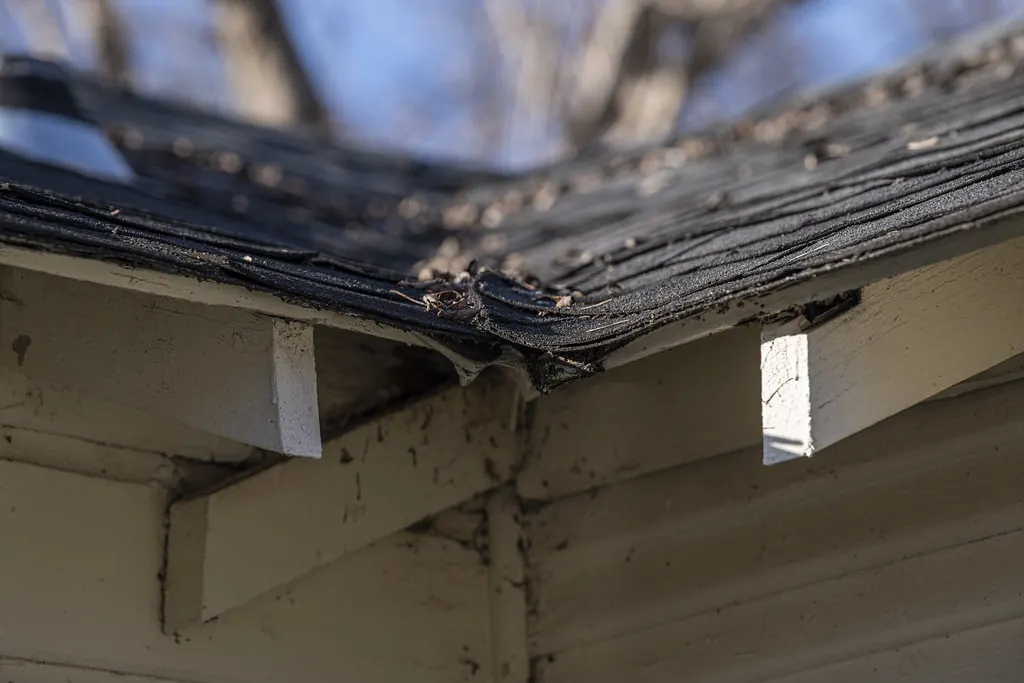
Typical gap: roof math, matching and missing trades
Arizona’s claim calendar
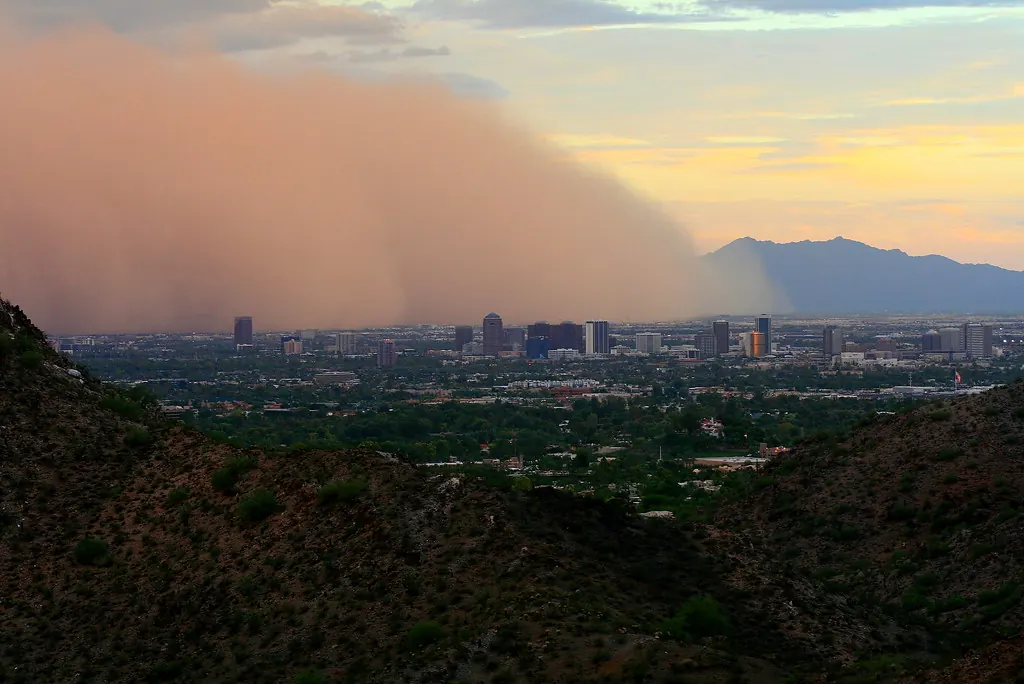
The monsoon officially runs June 15 to September 30. Wildfire season usually peaks before it, the high country freezes after it, and the heat never really leaves the low desert. An Arizona Insurance Appraiser has to know what each season does to a roof, a wall and an estimate.
Bands show typical timing. Storms do not read calendars: the October 2010 Phoenix hailstorm arrived well after the monsoon.
What we appraise
From one estimate review to full panel representation and neutral umpire work, each service is built around a single job: a valuation of your loss that holds up.
Two-number gap check
Type in the two figures you already have. If the difference is large, a conversation with an Arizona Insurance Appraiser makes sense. If it is small, a documented supplement request is often faster and cheaper.
The full appraisal payoff estimator adds fees and shows your break-even point.
From first call to signed award
The appraisal clause turns an open-ended argument into a process with a binding result. Here is how Arizona Insurance Appraiser takes a file from first call to signed award.
Read the full appraisal roadmapWe read your policy, the carrier’s estimate and your photos, then tell you plainly whether appraisal is the right tool.
Measurements, tile counts, moisture readings and photographs, building our own scope from the ground up.
An estimate priced for your Arizona ZIP code, with code items, permits and overhead and profit handled correctly.
The written demand goes out, appraisers are named, and we work line by line with the carrier’s appraiser.
Items still in dispute go to a neutral umpire. Two signatures set the amount of loss, and payment follows under the policy.
Four Arizonas
Dust storms in Mesa, flash floods in Tucson washes, snow on Flagstaff roofs and 118°F afternoons in Lake Havasu City. An Arizona Insurance Appraiser has to price each one with local knowledge.
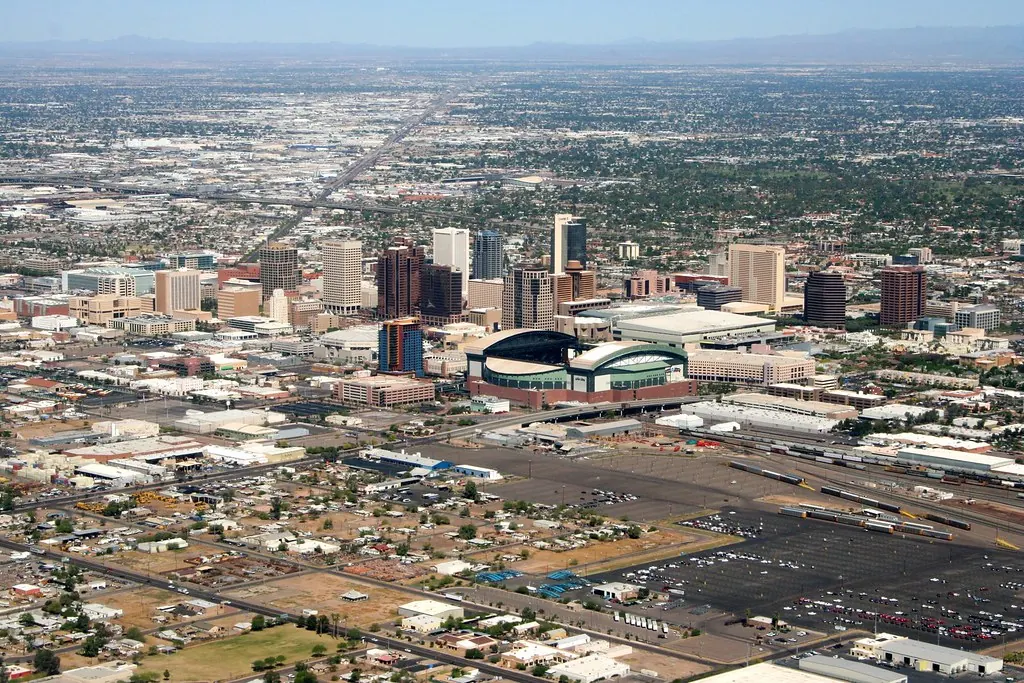
Phoenix · Mesa · Chandler · Scottsdale
Microbursts, dust storms and hail over concrete tile, foam roofs and block walls. Slab leaks and HOA matching disputes are everyday files.
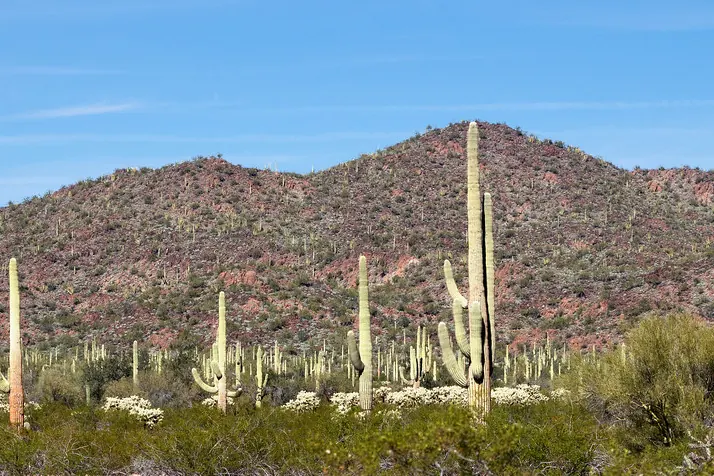
Tucson · Sierra Vista · Green Valley
Mountain-born monsoon storms, wash flooding, flat roofs with parapets and wildfire on the sky islands.
Flagstaff · Prescott · Show Low · Payson
Wildfire and post-fire flooding, snow load, ice dams and frozen pipes in cabins and second homes.
Yuma · Lake Havasu City · Kingman
Extreme heat, monsoon gusts, wash flooding and water losses in seasonal homes that sit empty all summer.
Free & private
Run the numbers before you call. Every tool works in your browser; nothing is stored or sent.
Open the calculators Calculator
 Calculator
 Calculator
 CalculatorPlanner
 ChecklistArizona tool
Statewide coverage
We serve all 15 counties, from Apache to Yuma. These are the communities where we see the most claims.
Clearing things up
Appraisal is only for huge commercial claims.
Most of our files are homes. If the gap is meaningful after fees, appraisal can fit a residential claim.
The appraisal panel decides whether I’m covered.
No. Appraisal decides the amount of a covered loss. Coverage disputes belong with an attorney.
My contractor can be my appraiser.
Policies usually require an independent appraiser. A contractor who will do the work invites a challenge.
Asking for appraisal stops every deadline.
Not automatically. Suit limitation and other deadlines may keep running, so calendar them.
Questions
Straight answers about how appraisal works, what it costs and when it is the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. Named as your appraiser, we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
A public adjuster manages and negotiates your entire claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the carrier’s final estimate, and the gap between it and your contractor’s number is meaningful, usually more than about 10% or several thousand dollars.
On the amount of loss, generally yes, once two of the three panel members sign. That is why documentation matters before anyone invokes appraisal.
Each side pays its own appraiser and usually half the umpire’s fee. We put our fee in writing before any work begins, and the first conversation is free.
Yes. We work in all 15 counties, including metro Phoenix, Tucson, Flagstaff, Prescott, Yuma, Lake Havasu City and Sierra Vista.
Articles
Practical guides from the Arizona Insurance Appraiser team on documentation, roofs, wildfire and your options.
Jul 14, 2026 · 7 min read
The first 72 hours after a microburst decide how strong your claim will be. Here is what to capture before cleanup erases the evidence.
Aug 25, 2026 · 8 min read
Concrete tile can outlast the felt beneath it by decades. That mismatch is behind most tile roof disputes in the Valley and Tucson.
Jun 10, 2026 · 7 min read
Homes that never burned can still need far more than a wipe-down. Here is how to document smoke and ash damage after a wildfire.
Monsoon season is claim season
A short review now can keep you from accepting a payment that will not cover the repair.
Start with a conversation
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing.
